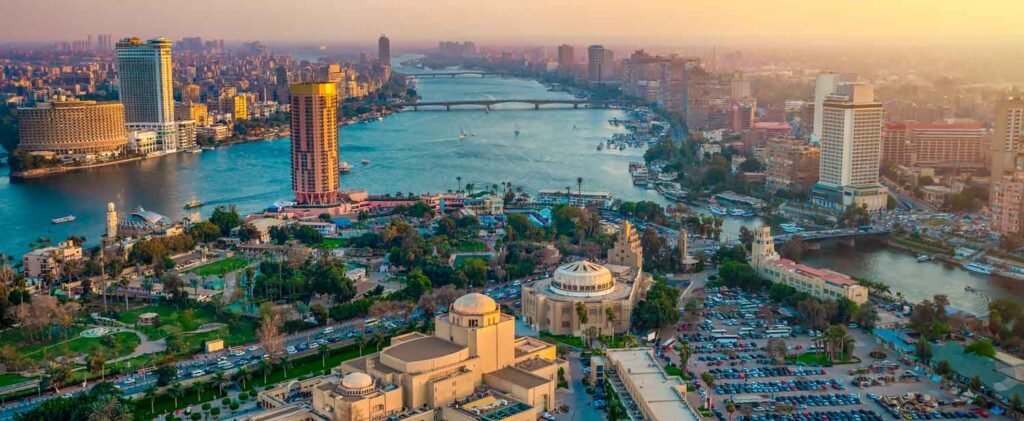
For the second phase of its Development Policy Financing (DPF) program, which supports structural reforms targeted at enhancing the business environment, bolstering economic resilience, and expediting the nation’s green transition, Egypt and the World Bank have reached a $1 billion financing agreement. The agreement was signed by Alwaleed Alatabani, the World Bank’s Division Director for Egypt, and Egyptian Foreign Minister Badr Abdelatty, who is also Egypt’s governor at the World Bank.
“Building Resilience, Creating Opportunities and Enhancing Wealth for Egypt’s Prosperity and Stability” is the name of the program, which aims to support reforms that increase Egypt’s economic competitiveness, fortify its resilience to external shocks, and accelerate the country’s shift to a green economy. The second phase of the program focuses on a set of structural changes pertaining to the governance of state-owned enterprises. These include lowering the cost of borrowing for the government, enhancing fair competition, removing barriers to private investment and growth, and boosting domestic tax mobilisation. The deal is a component of the government’s initiatives to secure development funding from regional and international organisations in order to promote economic resilience. Additionally, it backs Egypt’s initiatives to boost green development, increase competitiveness, and foster an investment climate that encourages the creation of jobs.
Also Read:
A Foreign Bank Branch With a UAE Licence Faces a Financial Penalty of Dhs 200,000,000 From CBUAE
On Emirates Road, a Truck Collides with a Metal Barrier While the Driver is Asleep
About Author