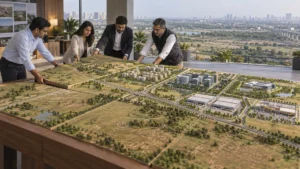
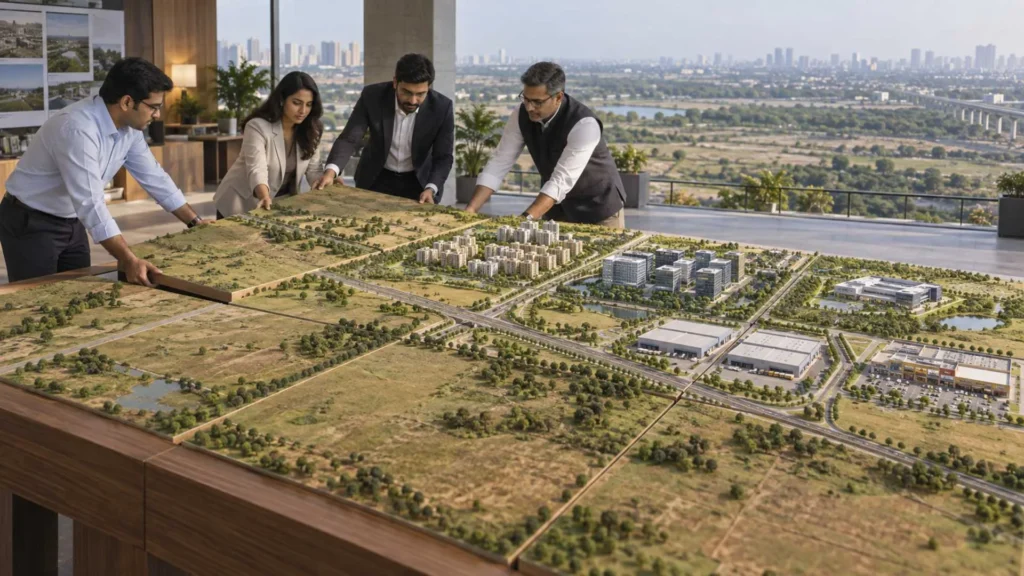
According to a Cushman & Wakefield assessment, India’s land markets have a potential income of $176 billion (16.7 lakh crore), which is over 22 times the revenue of the country’s top 10 listed real estate businesses by market size in FY26.
By 2036, India’s urban population is expected to increase from 555 million in 2026 to about 600 million, or three to four new cities the size of Bengaluru. This is backed by institutional investors investing $8 billion a year and consistent central government capital expenditures (over 10 trillion for three years, anticipated 12.2 trillion in FY27) through programs like Gati Shakti and Bharatmala. Transparency has increased and transaction friction has decreased thanks to policy changes, especially the Digital India Land Records Modernisation Program (99.8% land record digitalisation, 97.4% cadastral mapping).
From 813 acres in 2021 to 6,181 acres in 2025, the annual transacted acreage increased by almost seven times, representing a 66% CAGR. In Q1 2026, 1,194 acres had already been transacted. While Tier-I cities account for 71% of the total, Tier-II markets are growing rapidly, from 2% of annual volume in 2021 to 67% in Q1 2026 (mostly due to Visakhapatnam’s data center-related activities).
Large-scale townships and industrial parks are made possible by the divergence of average deal sizes: Tier-I parcels shrank from 21 to 10 acres (2021–Q1 2026), whereas Tier-II parcels grew from 8 to 53 acres.
Also Read:
The UAE Strengthens its Financial Collaboration with the BRICS
EGA has Acquired 80% of Eco Green, an Italian Company That Recycles Aluminium
About Author