A company can receive its trade licence and still have an important task ahead: arranging a business bank account. In the UAE, founders may come across instant IBAN services alongside the more familiar process of opening an account through a traditional bank. Both can lead to business banking, but the application experience, time to receive account details and available services may differ. Choosing wisely helps companies plan.
What does an instant IBAN offer?
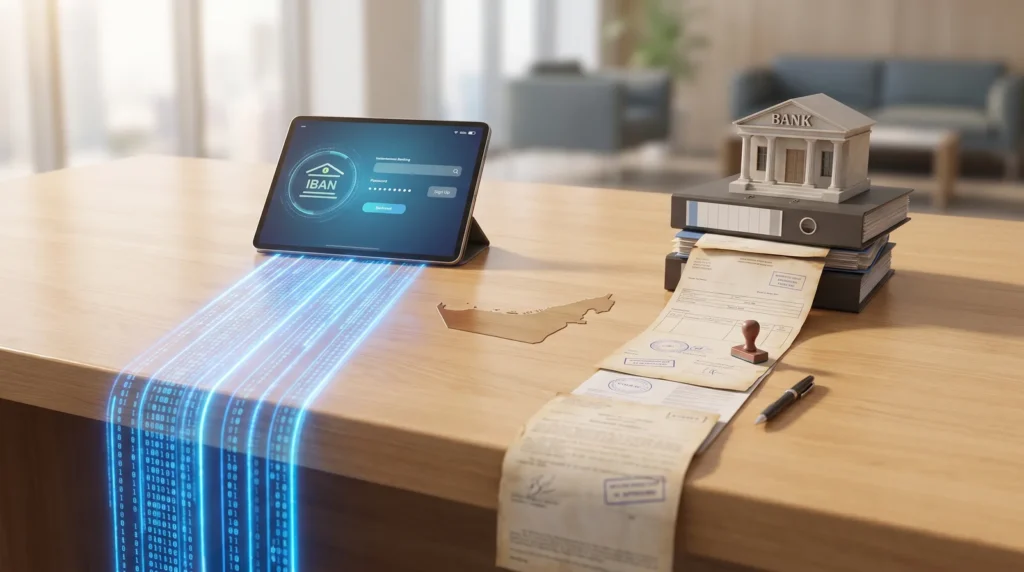
An International Bank Account Number (IBAN) identifies a bank account for local and international transfers. In an instant IBAN process, the bank generally uses digital onboarding so eligible applicants can submit documents online and potentially receive account details after initial verification. This suits a small service company preparing invoices.
The word “instant” needs some care. Receiving an IBAN does not necessarily mean every transaction feature is active. A bank may still be reviewing ownership, source of funds or the intended use of the account. Founders should ask when they can receive payments, send transfers and use any additional services, rather than treating an assigned number as final approval.
How traditional business account opening works
A conventional application may involve a relationship manager, a branch appointment and a more detailed review before the account is opened. The bank might request explanations of the company’s trading model, customers, suppliers or shareholder structure. These extra conversations can feel slower, but they may be useful for businesses with complex requirements.
For example, an import-export company with several shareholders may want regular international transfers, trade finance or help managing higher transaction volumes. A traditional banking relationship can make it easier to discuss these needs with a named contact. Availability depends on the bank.
Speed, features and costs: the practical comparison
Digital-first applications often move faster for straightforward company structures because document submission and identity checks happen remotely. Traditional applications may take longer when meetings and additional checks are required. Neither route comes with a universal approval deadline; incomplete records, higher-risk sectors and multi-layered ownership can delay either one.
The features matter as much as the timeline. A digital account may cover everyday transfers, payments and online administration, while a conventional bank may offer relationship management, cash handling or trade-related facilities. Availability varies by provider. Likewise, monthly charges, minimum-balance rules, transfer fees and currency conversion costs are set by the particular bank and product, not simply by whether the onboarding is digital or traditional.
Documents and compliance checks apply to both
Banks generally need to identify the company and the people behind it. Common requests include a valid trade licence, incorporation records or Memorandum of Association, shareholder and authorised signatory information, passports, and proof of address. An Emirates ID may be required where applicable. A bank may also ask for a brief business profile, expected transaction volumes or supporting contracts.
The important point is that digital onboarding does not remove know-your-customer obligations. Both routes remain subject to the bank’s due diligence and relevant UAE regulatory requirements. Keeping company names, ownership details and signatory authority consistent across documents reduces avoidable questions. Explain how customers pay and where funds originate.
Which route is better for a new UAE company?
The answer depends on the company’s first-year needs. A single-owner consulting firm with modest payment volumes may value a remote application and quick access to account details. A trading business with multiple shareholders, cross-border suppliers or plans for financing may prefer the wider services and direct support available at some traditional banks.
Founders comparing instant IBAN vs traditional business account opening in the UAE should look beyond the advertised opening speed. Check whether the bank accepts the relevant business activity and ownership structure, what functions are available immediately, and whether any restrictions apply during the final review. Some businesses may begin with a simpler account and later add another banking relationship as requirements develop.
Make the banking decision part of business setup
Companies established through Meydan Free Zone can explore available assistance in preparing bank applications and identifying suitable banking options. The bank retains final approval and activation authority.
The most useful comparison is therefore not “instant versus slow”. It is whether the opening process, costs, services and compliance requirements fit the company you are building. Choosing with those factors in mind can prevent the need to change accounts just as business activity begins to grow.
About Author